Lumen Vietnam Fund

Blog

Higher interest rates reshape valuations across Vietnamese asset classes

Higher interest rates reshape valuations across Vietnamese asset classes

Deposit rates remain elevated in Vietnam, while the outlook for lower lending rates remains uncertain. As bank deposits return yields of 6-8% a year, stocks, property, bonds, gold and foreign currencies are all facing a higher return benchmark in the competition for capital.

In the interbank market, short-term liquidity pressures have eased significantly after sharp fluctuations in September. On September 21, overnight lending rates briefly rose to 7% per year, about 2.5 percentage points higher than at the end of the previous week.

By September 24, the rate had fallen to 1% per year, while one-week rates stood at 5.1%, two-week rates at 5.2% and one-month rates at 6.15%. On September 28, the overnight rate declined further to 0.48%.

The easing of interbank rates indicates that immediate liquidity stress has subsided, but deposit rates at commercial banks have not fallen correspondingly.

By mid-September, the four largest state-owned banks maintained deposit rates of around 6.6% per year for six-month terms and about 6.8% for 12-month terms. At some joint-stock commercial banks, 12-month deposit rates were between 7% and 7.8%. Some special deposit products offered higher rates, but these do not represent the broader market level.

The gap between interbank rates and deposit rates reflects two different pressures. Short-term liquidity conditions can improve quickly after policy measures, while banks' funding costs depend on credit demand, competition for deposits and the need to secure capital for the final months of the year.

KB Securities Vietnam (KBSV) said deposit rates had reached their peak and could remain elevated in the third quarter before easing slightly from early in the fourth quarter. Vietcombank Securities (VCBS), however, continued to highlight funding pressure as credit growth is expected to remain high.

Deposit growth reached 8.77% in August from the end of 2025, higher than credit growth of 8.38%. The gap has helped ease some pressure on the banking system's funding sources, but it is not enough to confirm that deposit rates will decline soon.

The final months of the year are typically a period when credit demand rises rapidly. If demand for capital continues to expand, banks may need to maintain sufficiently attractive deposit rates to retain funds.

Exchange rates are another constraint on the ability to cut rates. In September, the U.S. Federal Reserve raised interest rates by 25 basis points, bringing its target range to 3.75-4%. New projections from Federal Open Market Committee members showed that room for further monetary tightening remained.

Banking expert Nguyen Tri Hieu said U.S. interest-rate developments continued to affect exchange rates and Vietnam's monetary policy room.

When U.S. bond yields rise and the dollar remains strong, rapid domestic rate cuts become more difficult. If interest-rate differentials narrow too much, pressure on the exchange rate could increase, potentially feeding back into inflation.

The current environment therefore appears more consistent with a scenario of less volatile but still elevated interest rates, rather than a broad-based rapid rate-cut cycle.

Vietnam's credit-to-GDP ratio is currently around 150%. The large scale of credit means monetary management cannot rely mainly on further credit expansion, but must also focus on controlling the quality of capital allocation.

In this environment, high interest rates are beginning to have a clearer impact on how investors value different asset classes.

Property market faces pressure from funding costs

Property is among the markets most sensitive to interest rates. When deposit rates rise, banks' funding costs increase, limiting their ability to reduce lending rates.

For highly leveraged property companies, higher financial costs continue to weigh on cash flows, profitability and project development progress.

In a property sector report released in July, brokerage MBS said the residential property market in 2026 was being affected by high interest rates, causing liquidity and absorption rates to slow. The northern and southern markets were also showing different trends.

Greater pressure was falling on projects that had yet to generate cash flows, as developers may need to extend restructuring efforts, sell assets or seek financially stronger partners.

Segments serving genuine housing demand or generating clearer cash flows are proving more resilient. Industrial property has its own growth drivers thanks to foreign direct investment inflows and land rental demand, but each company's performance still depends heavily on legal progress, land handover schedules and revenue recognition timing.

For individual investors, the current interest-rate environment is changing investment calculations.

When 12-month deposits can generate returns of 6-8% per year, a low-liquidity property asset with high transaction costs and no cash flow must deliver sufficient price appreciation to compensate for the foregone yield.

Assets driven mainly by expectations of future price increases therefore face greater pressure than those with real demand or stable income generation.

Stocks face selective rather than broad-based gains

For equities, interest rates affect both capital flows and valuations. Higher deposit rates increase the opportunity cost of holding stocks. When safer assets offer higher returns, investors also demand higher returns from riskier assets. This puts pressure on the valuation multiples investors are willing to pay.

However, high interest rates do not necessarily mean money will leave equities if corporate earnings continue to grow.

SSI Securities's research unit said interest rates had not fallen significantly, while earnings prospects in the second half of the year could be less impressive than in the first half. Investment focus was therefore shifting towards sector and company selection rather than expectations of a broad market rally.

Banks are directly affected by funding costs. Banks with high CASA ratios, strong deposit mobilization and stable asset quality have an advantage in maintaining net interest margins, while those that need to raise deposit rates aggressively face greater pressure on funding costs and profits.

For listed property companies, pressure comes from both higher financial costs and weaker demand as buyers using leverage face higher borrowing costs.

Companies in manufacturing, exports, infrastructure, power and logistics with relatively stable operating cash flows may be less affected by the property credit cycle. However, this advantage still depends on each company's capital structure, industry outlook and ability to sustain earnings.

High interest rates are therefore making the market more differentiated rather than moving all asset classes in the same direction.

Bonds, gold and foreign currencies

The corporate bond market is also facing direct pressure as bank deposits become more attractive.

To compete for capital, bonds need to offer yields high enough to compensate for credit risks, particularly for property companies with weak cash flows or large refinancing needs.

HNX data showed that in September, some five- to six-year bank bond issuances carried interest rates of around 8.2-9% per year.

MBS also announced that the interest rate applicable to the fifth and sixth interest periods of its MBS12501 bond was 8.1% per year.

These levels show that funding costs in the bond market remain significant, creating an advantage for companies with strong cash flows, sound financial foundations and high transparency. For weaker companies, issuing new bonds to refinance existing debt will become increasingly difficult.

Gold and foreign currencies are also facing stronger competition from deposits.

When VND interest rates remain high, the opportunity cost of holding non-income-generating assets rises.

For gold, support continues to come from geopolitical uncertainty, global monetary policy and demand for hedging. However, to attract domestic capital, gold prices need to rise enough to compete with the returns available from bank deposits.

On September 29, domestic gold prices continued to fluctuate sharply, while global gold prices faced pressure from expectations that U.S. interest rates would remain elevated.

The domestic exchange rate has shown signs of easing. On September 29, the State Bank of Vietnam set the central exchange rate at VND25,630 per U.S. dollar, down VND2 from the previous session. However, the dollar remains heavily influenced by U.S. bond yields and expectations for Fed policy.

When bank deposits offer returns of 6-8% a year, investment channels with higher volatility must generate sufficiently large returns to compensate for risk, liquidity constraints and funding costs.

Capital is therefore unlikely to flow broadly into a single market. The ability to generate cash flow, leverage levels and asset quality will determine the attractiveness of each investment option while interest rates remain elevated.


Source: Dinh Vu, Thai Ha

Photo: Illustration courtesy of Robinson Appraisal Group LLC
Latest Posts

PM orders urgent measures to ensure power supply for 2027–2030

PM orders urgent measures to ensure power supply for 2027–2030

The PM stressed that national energy security and an adequate electricity supply are fundamental to achieving socio-economic development goals and constitute a particularly important political task for the entire political system.

Hanoi (VNA) – Prime Minister Le Minh Hung has ordered ministries, localities and relevant agencies to urgently implement measures to ensure sufficient electricity supplies from 2027 to 2030 and beyond, stressing that power shortages must not occur under any circumstances.

The Government Office issued Official Dispatch No. 10790/VPCP-CN on October 22, conveying the PM’s instructions to the Minister of Industry and Trade, secretaries of provincial and municipal Party committees, and chairpersons of provincial and municipal People’s Committees.

The PM stressed that national energy security and an adequate electricity supply are fundamental to achieving socio-economic development goals and constitute a particularly important political task for the entire political system.

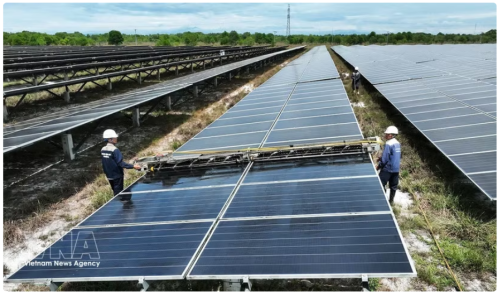
In the immediate term, the ministry is requested to direct and urge ministries, agencies and localities to expand self-produced and self-consumed rooftop solar power at households, offices, public buildings and production and business establishments. The installation of battery energy storage systems (BESS) should also be encouraged to reduce peak-hour demand and increase on-site power self-sufficiency.

The ministry must propose targets for rooftop solar power development in each locality, particularly in northern provinces, specifying installation numbers and deadlines for operation. The proposal must be completed before October 30, with implementation results serving as an important criterion for assessing the performance of ministry and local leaders.

Besides, it must guide and urge localities to introduce support policies for households installing self-produced and self-consumed solar systems in this December. Investors are required to ensure that the Na Duong 2 and Quang Trach I thermal power plants are completed and begin commercial operation in 2026.

The ministry must accelerate eligible concentrated solar power projects, floating solar installations on hydropower reservoirs and associated grid infrastructure included in the revised Power Development Plan VIII. Priority should be given to projects in northern areas, including the Lai Chau and Son La hydropower reservoirs. Vietnam Electricity (EVN) is tasked with studying and investing in BESS at substations and other suitable locations, with the systems scheduled to operate in 2027.

By December, the ministry, in coordination with the Ministry of Finance, the Ministry of Justice and relevant agencies, must develop mechanisms and guidelines to accelerate energy storage development, particularly rooftop solar combined with BESS in industrial parks and clusters in northern provinces.

The PM also called for stronger electricity-saving measures, requiring annual savings of at least 3% of national power consumption and at least 10% during peak hot-weather months from April to July. Demand management and load shifting must help reduce peak-hour demand by at least 3,000 MW, while cutting power losses across the system to below 6%.

For 2028–2030 and subsequent years, the ministry must work with the Ministry of Finance and major state-owned groups, including EVN, the Vietnam National Industry – Energy Group (Petrovietnam) and the Vietnam National Coal and Mineral Industries Group, to review power generation and transmission projects and assign clear responsibilities for implementation.

The ministry must identify project delays, financing difficulties and obstacles requiring resolution. If necessary, it should propose using State budget funds for urgent power projects and report to the PM before October 30, 2026.

The PM warned against lax oversight after investment licences are issued and called for strict action against investors that delay projects or violate regulations. The ministry will bear responsibility if planned projects are not implemented or fail to enter operation on schedule. It must also take final responsibility if electricity shortages occur under any circumstances.


Top Vietnamese leader holds talks with European Council President

Top Vietnamese leader holds talks with European Council President

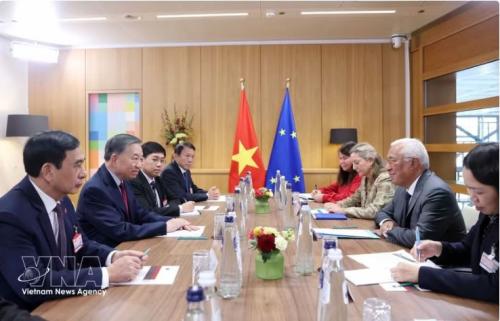
At their talks in Brussels on October 22, the two leaders agreed to explore and promote maritime economic cooperation as a new pillar of bilateral relations.

Talks between General Secretary of the Communist Party of Vietnam Central Committee and President To Lam and European Council President António Costa was held in Brussels on October 22 as part of the former's official visit to the European Union (EU).

At the talks, President António Costa, as cited by the Vietnam News Agency, warmly welcomed General Secretary and President To Lam and the high-ranking Vietnamese delegation on their official visit to the EU. He fondly recalled his deep impressions of Vietnam and its people, as well as the warm and cordial reception extended by the Vietnamese side during his visit in early January this year.

The two leaders’ early reunion reflects the increasingly deep political trust between Vietnam and the EU, he stressed.

Vietnam is an important partner of the EU in the Indo-Pacific region, he said, expressing confidence that both sides would continue to build on their foundation of political trust and positive cooperation outcomes to deepen their Comprehensive Strategic Partnership, bringing tangible benefits to both sides.

Expressing his pleasure at visiting the EU for the first time in his new capacity, General Secretary and President To Lam, as quoted by the news agency also, spoke highly of the role played by the European Council and President António Costa personally in shaping the EU’s strategic priorities, promoting unity and consensus among member states, strengthening the bloc’s self-reliance and resilience, and contributing to peace, stability, cooperation and development in the region and around the world.

Vietnam regards the EU as one of its top-priority partners, with substantial shared interests and long-term cooperation potential. It wishes to translate commitments into concrete outcomes and practical cooperation projects that will support development and improve the lives of people on both sides, the Vietnamese leader noted.

General Secretary and President To Lam and President António Costa welcomed the positive progress in Vietnam-EU relations after more than 36 years of diplomatic ties, particularly following the elevation of bilateral relations to a Comprehensive Strategic Partnership in January 2026, the news agency reported.

Amid complex regional and global developments, the two leaders agreed that Vietnam and the EU should strengthen dialogue, contacts and exchanges at all levels, particularly at the high level, to consolidate political trust and enhance mutual understanding. They also agreed to improve cooperation effectiveness and create breakthroughs by expanding collaboration into new areas aligned with the development priorities of both sides, including green transition, innovation, strategic infrastructure and the circular economy.

Sharing a vision for developing a blue economy, protecting the oceans and ensuring maritime security, the two sides agreed to explore and promote maritime economic cooperation as a new pillar of bilateral relations.

General Secretary and President To Lam called for deeper economic, trade and investment ties, and for the two sides to continue fully capitalizing on the potential and advantages offered by the EU-Vietnam Free Trade Agreement (EVFTA). He thanked the EU for recognizing Vietnam’s efforts and removing the country from Annex I of the list of non-cooperative jurisdictions for tax purposes. He also called on both sides to work closely together to swiftly resolve longstanding outstanding issues, including the removal of the “yellow card” warning on Vietnamese seafood over illegal, unreported and unregulated (IUU) fishing, and the early ratification of the EU-Vietnam Investment Protection Agreement (EVIPA).

President António Costa affirmed the EU’s desire to further deepen substantive cooperation with Vietnam by effectively leveraging EU programs and initiatives, such as the Global Gateway, to promote high-quality investment, develop sustainable connectivity infrastructure and advance the energy transition.

The EU will continue promoting cooperation, sharing experience and building capacity in maritime security and safety, cybersecurity and crisis management, as well as coordinating in responding to non-traditional challenges, particularly climate change and emerging technological challenges, including artificial intelligence, in line with the needs, priorities and shared interests of both sides, he said.

On this occasion, the two leaders also held in-depth and wide-ranging discussions on regional and international issues. They agreed to strengthen exchanges, consultations and coordination at multilateral forums; uphold multilateralism, the United Nations Charter and international law; and further promote ASEAN-EU relations, thereby making positive contributions to maintaining peace, stability, cooperation and development in the Indo-Pacific.

President António Costa emphasized that the EU attaches importance to advancing relations with ASEAN, with Vietnam as one of its leading partners, as the EU and ASEAN work towards upgrading their ties to a Comprehensive Strategic Partnership in 2027, when they will mark the 50th anniversary of their relations.

He reaffirmed the EU’s continued support for ASEAN centrality and for ASEAN’s and Vietnam’s positions on promoting the peaceful settlement of disputes in accordance with international law, particularly the 1982 United Nations Convention on the Law of the Sea (UNCLOS), ensuring peace, stability, security, safety and freedom of navigation and overflight in the seas and oceans.


Institutional reforms provide boost for business growth

Institutional reforms provide boost for business growth

Institutional reform should go beyond reducing red tape to build business confidence and encourage companies to invest and expand operations.

Hanoi (VNA) - Cutting administrative procedures, resolving legal bottlenecks and unlocking resources are key solutions to improve the business environment, give companies greater confidence to invest and strengthen their competitiveness, helping drive sustainable growth.

For businesses, the quality of the business environment is reflected in the time required to complete administrative procedures, compliance costs, access to capital and land, and policy stability. Institutional reform, therefore, should go beyond reducing red tape to build business confidence and encourage companies to invest and expand operations.

Nguyen Xuan Tho, Deputy Director of the Agency for Private Enterprise and Collective Economy Development under the Ministry of Finance, said the ministry has proactively reviewed practical conditions and advised the Government to issue Resolution No. 02/NQ-CP on key tasks and solutions to improve the business environment and enhance national competitiveness in 2026, with seven priority groups of measures and specific responsibilities assigned to ministries, sectors and localities.

The measures focus on improving the institutional framework, reviewing conditional business lines, streamlining administrative procedures, unlocking resources and supporting businesses. The goal is not merely to refine regulations, but to remove barriers directly affecting investment, production and business operations.

In the first nine months of 2026, efforts to review and improve the legal framework were stepped up. At the first session of the 16th National Assembly, lawmakers passed nine laws and 31 resolutions to promptly translate development policies into law.

The Ministry of Finance also advised on the refinement of various policies on investment, corporate income tax, personal income tax and tax administration, aiming to address shortcomings identified in practice.

One notable development has been the expansion of financial support for businesses. In the nine-month period, the ministry advised on and implemented tax, fee and charge exemptions, reductions and payment extensions worth a total of about 245.6 trillion VND (9.5 billion USD). These measures have helped ease cash-flow pressures, sustain business operations and free up resources for investment.

Another area of reform is strengthening dialogue with businesses and addressing their concerns. Tho said that, to date, ministries and agencies had responded to and fully resolved 146 of the 202 groups of business recommendations.

From the business community’s perspective, the gap between policy and implementation remains a major bottleneck in the business environment.

Ho Sy Hung, Chairman of the Vietnam Chamber of Commerce and Industry (VCCI), said businesses could have different experiences with the same regulation depending on the locality.

Decisive implementation can help companies benefit from policies sooner, while delays elsewhere may cause them to miss investment and business opportunities, he elaborated.

In July 2026, VCCI compiled nearly 900 specific concerns raised by businesses into 53 groups of issues across 10 sectors. The feedback showed that businesses need not only individual administrative procedures to be resolved, but also a stable, consistent and predictable policy environment, Hung said.

Hung said that while the previous phase focused on breakthroughs in institutional reform, the next should place greater emphasis on breakthroughs in implementation.

Reform should therefore be measured not simply by the number of amended regulations or procedures cut, but by whether policies are implemented consistently, processing times are genuinely shortened and business costs are reduced, he added.

To narrow this gap, Tho suggested ministries, sectors and localities improve the quality of lawmaking, resolutely remove barriers to market access, further simplify administrative procedures, make processes transparent and standardise how business recommendations are received and addressed.

Digital transformation in public service delivery should go hand in hand with reducing unnecessary face-to-face interactions, curbing informal costs and strengthening dialogue to resolve problems at an early stage, he said.

Tho also proposed reforming state management by shifting from pre-inspection to post-inspection, as appropriate for each sector, based on clear standards and technical regulations and stronger risk-based oversight.

Business environment reforms should also be aligned with the goal of improving growth quality. Nguyen Duc Hien, deputy head of the Party Central Committee’s Commission for Policy and Strategy, stressed that in the new phase, promoting the private sector, harnessing the potential of all economic sectors, and advancing science and technology, innovation and digital transformation are key foundations for achieving the target of double-digit economic growth.

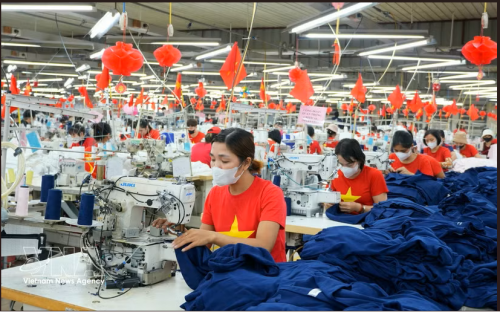
Hien said traditional growth drivers need to be revitalised to meet new development requirements. For exports, the focus should go beyond increasing turnover to raising value added, boosting the share of value created domestically and setting appropriate development directions for each industry group.

Sectors with the potential to drive growth and generate spillover effects, including research and development (R&D), tourism, logistics, energy, and finance and banking, need to be promoted.

Meanwhile, established industries such as electronics, digital technology, textiles and garments, footwear, and food processing should continue to upgrade product quality, strengthen technological capabilities and increase domestic value added, Hien suggested.​

See all blog