Lumen Vietnam Fund

Blog

Domestic investors shield Việt Nam bonds from global sell-off

Domestic investors shield Việt Nam bonds from global sell-off

Việt Nam’s government bonds have weathered global turmoil, but rising yields could still raise domestic borrowing costs.

HÀ NỘI — Government bonds in major economies have come under heavy selling pressure in recent weeks, but Việt Nam’s bond market has remained relatively calm, largely because foreign investors play only a small role in it.

Yields on 10-year government bonds have climbed to multi-year highs in several major markets. Japan’s 10-year yield recently reached 3 per cent, its highest level since 1996, while the US 10-year Treasury yield has risen to about 4.8 per cent. UK and German government bond yields have also reached their highest levels in more than a decade.

In Việt Nam, the 10-year government bond yield stood at 4.43 per cent in early September, up about 0.4 percentage points from the beginning of the year. The increase is noticeable but has been far less dramatic than in some developed markets.

The market is largely protected by its domestic investor base, which holds most Vietnamese government bonds and limits the scope for sudden foreign selling.

“Việt Nam benefits from a large and relatively stable domestic investor base, which helps cushion the market from short-term international capital-flow volatility,” said Sana Ur Rehman, senior market analyst at EBC Financial Group.

At the end of last year, banks and insurers held 98.7 per cent of Việt Nam’s local-currency government debt at the end of 2025, with foreign ownership remaining marginal, according to the Asian Development Bank.

That share is far below those in several other emerging Asian markets, including Malaysia, Indonesia, Thailand and the Philippines.

The structure gives Việt Nam’s bond market a degree of protection when global investors rush to cut risk.

When bond yields rise sharply in major economies, international funds often reassess emerging-market holdings because safer assets, particularly US Treasuries, become more attractive. Some funds may also sell emerging-market bonds to reduce the average maturity of their portfolios.

Still exposed to global risks

But Việt Nam is not immune to global risks.

The global rise in borrowing costs is already beginning to affect the price at which Việt Nam can raise money. At a State Treasury auction on September 9, five-year bonds were sold at a yield of 4.26 per cent and 10-year bonds at 4.43 per cent. The 10-year yield was up from around 4.16 per cent at the end of April.

Demand remained strong enough for both offerings to be fully allocated, although there were no successful bids for three-year bonds and no bids for 15-year and 30-year bonds.

The results suggest investors are becoming more selective rather than abandoning the market.

Global yields affect Việt Nam mainly through the exchange rate, inflation and domestic interest rates. According to Rehman, when US Treasury yields rise, the US dollar can become more attractive, putting pressure on the đồng. If that pressure becomes strong, monetary authorities may need to manage liquidity or use foreign-exchange reserves, which can push domestic short-term rates higher.

Higher global yields also raise the return investors expect from other assets. For Vietnamese companies seeking foreign-currency loans, syndicated financing or international investment, the cost of capital can therefore rise even without a large-scale sale of domestic government bonds.

The effect is already more visible in the corporate bond market.

MB Securities Co estimates that corporate bond issuance reached about VNĐ322.3 trillion in the first seven months of 2026, up 2.7 per cent year-on-year, while the weighted average issuance rate rose to around 9.5 per cent, about 140 basis points higher than the beginning of the year.

Global demand for long-term capital is also rising, with five major US tech companies – Alphabet, Amazon, Meta, Microsoft and Oracle – issuing about US$220 billion in debt this year to fund data centres and AI infrastructure, according to LSEG data cited by Reuters. This is adding to competition for capital in emerging markets.

Việt Nam nevertheless enters this period with some advantages. Public debt was around 35-36 per cent of GDP at the end of last year, well below the statutory ceiling of 60 per cent. The country also has a large domestic institutional investor base, which provides relatively stable demand for government debt.

Rehman said a more liquid government bond futures market could give investors an additional tool to manage interest-rate risk and improve price discovery. While Việt Nam’s five-year and 10-year bond futures currently have no trading activity or open interest, he said such risk-management tools would become more important as the country develops a broader institutional investor base.

“Domestic demand provides an important foundation of stability for Việt Nam’s bond market," Rehman added.

"The next stage of development is to broaden the investor base and deepen the tools available for risk management, giving the market more channels through which to absorb volatility.”


Source: VNS

Photo: VNA/VNS
Latest Posts

Vietnam's $20.5 bln trade deficit: How FDI inflows are supporting the dong

Vietnam's $20.5 bln trade deficit: How FDI inflows are supporting the dong

Vietnam's $20.46 billion trade deficit in the first eight months has not translated into a corresponding rise in the USD/VND exchange rate. Disbursed foreign direct investment (FDI), along with other foreign currency inflows, is helping balance dollar supply and demand, but questions remain over the quality of these capital flows and their ability to generate net foreign currency for the economy.

Large trade deficit, but FDI creates a "matching source of dollars"

Vietnam recorded a trade deficit of $20.46 billion in the first eight months of 2026, with imports reaching $395.3 billion, up 35.3%, while exports rose 22.4% to $374.84 billion. In August alone, the trade deficit was just $120 million.

What is notable is that the exchange rate has not moved in the same direction as the trade deficit. According to the National Statistics Office, the U.S. dollar price index rose 1.31% year-on-year on average in the first eight months. In August alone, it fell 0.36% from a year earlier and 0.38% from December 2025.

Meanwhile, according to brokerage MBS, the interbank USD/VND exchange rate stood at 26,083 dong per dollar at the end of August, down 0.8% from the end of July and 0.7% from the start of the year.

Why has the large trade deficit not put corresponding pressure on the exchange rate?

Rong Viet Securities (VDSC) said import and export data do not fully reflect developments in the foreign exchange market. The value of goods crossing borders does not necessarily mean foreign currency payments arise immediately at the same time. Assessing exchange-rate pressure requires looking at actual foreign currency supply and demand.

Dr. Can Van Luc also said the trade deficit has some impact on the foreign currency balance and exchange rate, but not a significant one. He said the foreign currency balance is also supported by the VND-USD interest rate differential, disbursed FDI, remittances and international tourism. These flows help offset foreign currency demand generated by imports, allowing the USD/VND exchange rate to remain within a controlled range.

From this perspective, FDI has become one of the notable sources of foreign currency supply.

In the first eight months, total registered FDI reached $40.63 billion, up 55.4% year-on-year. Disbursed FDI stood at $17.25 billion, up 12% and the highest level for the first eight months in five years.

Notably, the FDI sector still posted a trade surplus of $10.14 billion, while the domestic economic sector recorded a deficit of as much as $30.6 billion. The FDI sector also accounted for 80.1% of total exports, at $300.37 billion.

Thus, in terms of the trade balance, the FDI sector is generating a significant amount of foreign currency through exports, helping offset the economy's foreign currency demand.

But this is only one side of the flow.

In the first eight months, the FDI sector also imported $290.23 billion worth of goods, up 40.1%. The sector is therefore both generating foreign currency revenue from exports and creating substantial dollar demand for imported machinery, components, raw materials and production inputs.

The key issue, therefore, is not just how much FDI flows into Vietnam, but how much net foreign currency this capital generates for the economy.

The FDI sector's $10.14 billion trade surplus has some significance for the foreign currency balance. Meanwhile, 94.1% of the country's imports were production inputs, indicating that most current dollar demand is linked to production, investment and the expansion of economic capacity.

Are FDI dollar inflows sustainable enough to support the dong?

If FDI is one of the important sources of foreign currency supply, the next question is whether these flows are large and stable enough to provide a "buffer" for the exchange rate in the final months of the year.

In reality, FDI is not the only source of foreign currency supporting the market.

Speaking to the media recently, expert Dao Hong Chau said companies increasing their foreign borrowing and selling dollars for dong could increase the supply of foreign currency sold into the market, thereby helping lower the dollar's value.

He said exchange-rate stability also has a positive impact on the ability to attract and retain foreign capital as investors become less concerned about the risk of dong depreciation.

Expert Nguyen The Minh said foreign currency supply is being supported by foreign currency credit, foreign borrowing by companies and banks, and disbursed FDI. A stable exchange rate, he said, helps ease pressure on inflation, macroeconomic balances and foreign currency-denominated debt obligations.

Thus, current exchange-rate movements do not depend solely on the trade balance but are also affected by various foreign currency flows. This is why a widening trade deficit does not necessarily translate into a corresponding rise in the dollar.

However, this should not be viewed as a condition that can automatically persist.

Eight-month data show imports by the FDI sector rose 40.1%, faster than the 26.9% growth in its exports. On the one hand, this reflects expanding production and investment activity; on the other, it shows that foreign currency demand for imported inputs remains substantial.

As disbursed FDI continues to rise and the FDI sector maintains a trade surplus, foreign currency inflows from the sector have a stronger basis for supporting the foreign currency balance. However, the extent of that support will also depend on import trends and other foreign currency flows.

VDSC also noted that exchange-rate pressure only emerges when foreign currency flows actually arise in the market. Therefore, looking only at the headline trade deficit to assess exchange-rate pressure could give an incomplete picture.

At present, foreign currency supply from disbursed FDI, foreign borrowing and other capital flows is creating a buffer for the foreign exchange market. At the same time, movements in the global dollar are also helping ease pressure on the USD/VND exchange rate.

Still, this "buffer" will only be sustainable if FDI continues to translate into production capacity, exports and value added in Vietnam.

In other words, exchange-rate pressure is not determined simply by how large Vietnam's trade deficit is, but, more importantly, by what sources of foreign currency the economy has to offset that deficit and whether those sources are sustainable.

For FDI, the current signals are relatively positive, with capital disbursement at its highest level in five years and the sector still posting a trade surplus of more than $10 billion. But the 40.1% increase in FDI-sector imports also shows that these dollar flows are moving in both directions.

FDI is therefore helping support the exchange rate, but for it to become a long-term anchor, what matters more is the ability to turn foreign capital inflows into a source of net foreign currency generation for Vietnam.


Vietnam, Thailand seek new momentum in Comprehensive Strategic Partnership

Vietnam, Thailand seek new momentum in Comprehensive Strategic Partnership

General Secretary and President To Lam emphasized that this marks the first visit to Vietnam by a Thai monarch in 50 years, since the two countries established diplomatic relations in 1976.

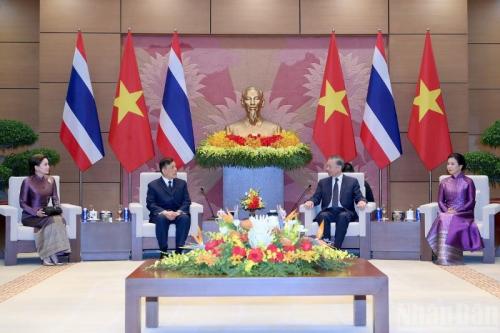
During their talks in Hanoi on September 15, Party General Secretary and State President To Lam and King of Thailand Maha Vajiralongkorn Phra Vajiraklaochaoyuhua agreed to continue strengthening political trust and promoting economic, trade and investment cooperation, people-to-people exchanges, and other areas, with a view to making the Vietnam-Thailand Comprehensive Strategic Partnership increasingly substantive, effective and sustainable.

The talks followed the official welcoming ceremony for the King and Queen, who are paying a State visit to Vietnam.

General Secretary and President To Lam emphasized that this marks the first visit to Vietnam by a Thai monarch in 50 years, since the two countries established diplomatic relations in 1976. The historic visit represents an important milestone in the traditional friendship between Vietnam and Thailand, particularly following the elevation of bilateral ties to a Comprehensive Strategic Partnership in 2025.

The two sides agreed to continue strengthening political trust by maintaining high-level visits and contacts, promoting the effectiveness of existing cooperation mechanisms, and effectively implementing the framework of the Vietnam-Thailand Comprehensive Strategic Partnership.

They also agreed to promote effective economic, trade and investment cooperation in a more interconnected and results-oriented manner; increase people-to-people exchanges and cooperation in education, culture and tourism; improve transport connectivity; and step up cooperation between localities, creating more substantive links and bringing bilateral relations to greater depth.

Mr. Lam spoke highly of activities and projects sponsored by the Thai Royal Family in Vietnam in the fields of education and community development, affirming that Vietnam will continue to coordinate with and facilitate the effective implementation of these activities.

The Vietnamese top leader also expressed his appreciation to the King and the Thai Royal Family for their affection toward Vietnam, particularly their attention to the Vietnamese community in Thailand and their efforts to preserve sites associated with President Ho Chi Minh. These sites serve as meaningful symbols of history, cultural exchange and friendship between the peoples of Vietnam and Thailand.

On regional and international issues, the two leaders praised the coordination between Vietnam and Thailand at multilateral forums and within regional and subregional cooperation mechanisms. They agreed to continue making positive contributions to strengthening ASEAN solidarity and unity and promoting the bloc's central role.

The two leaders expressed their confidence that the Thai King's and Queen's State visit to Vietnam would further strengthen friendship, political trust and mutual understanding between the peoples of the two countries, providing new momentum for the Vietnam-Thailand Comprehensive Strategic Partnership to develop in an increasingly substantive, effective and sustainable manner, and contributing to the building of an exemplary Vietnam-Thailand cooperative relationship.


Ministry clarifies proposal to ease conditions for foreign investors

Ministry clarifies proposal to ease conditions for foreign investors

The Ministry of Finance (MoF) is seeking comments on a draft amendment to the Investment Law, which proposes easing market access conditions for foreign investors.

The Ministry of Finance (MoF) is seeking comments on a draft amendment to the Investment Law, which proposes easing market access conditions for foreign investors.

During the consultation process, the proposal has received feedback from various ministries, agencies and businesses. Many have suggested that consideration be given to regulations governing sectors in which foreign investors would be permitted to own up to 100% of charter capital.

The State Bank of Vietnam (SBV) said that allowing 100% foreign ownership in sectors such as financial services, accounting, auditing and travel agency services would mean that foreign capital inflows and outflows would be larger and more sensitive to global interest rate and exchange rate movements, thereby increasing the risk of capital-flow reversals.

In response, the MoF said that, among the 91 conditional market-access sectors and subsectors, 10 currently only require the establishment of a joint venture but do not impose any foreign ownership cap. This means foreign investors are already entitled to own up to 99.9% of charter capital in these sectors.

Therefore, removing the joint-venture requirement would not materially change the scale of foreign capital flows into these sectors. Instead, it would primarily remove barriers to market access and reduce compliance costs, in line with the tasks set out in the Politburo's Resolution No. 10-NQ/TW and the Prime Minister's Decision No. 2014/QD-TTg dated September 12, 2026.

According to the Ministry of Finance, Clause 3a of Article 8 of the revised draft has also been amended to establish a general principle.

It stipulates: “Based on socio-economic conditions and State management requirements in each period, the Government shall consider and decide on the relaxation of market access conditions in sectors and industries subject to restricted market access for foreign investors as provided for in laws and resolutions of the National Assembly, ordinances and resolutions of the Standing Committee of the National Assembly, Government decrees and international investment treaties, ensuring publicity, transparency, consistent application and non-discrimination among investors.”

Compared with the first draft, the MoF has therefore removed the provision specifying “100% foreign ownership” of foreign investors.

For sectors in the finance and banking fields, the MoF said that any consideration of easing market access conditions, if applicable, must involve consultation with the SBV in its capacity as the sectoral regulator. It must also be subject to a comprehensive impact assessment, including its potential effects on the scale and structure of capital flows and on financial-system safety.

The ministry has asked the SBV to coordinate during the drafting of the detailed implementing decree.

Safeguards to prevent discretionary application

Commenting on the draft amended law, the Ministry of Industry and Trade proposed adding principles and criteria to prevent discretionary application of the provisions.

The Vietnam Association of Foreign-Invested Enterprises (VAFIE) also proposed making it clear that the Government may only make decisions based on a published list of sectors and a set of criteria. Any decision should clearly state its legal basis, scope, duration and conditions, and should be published on the National Single Window for Investment and subject to periodic review.

According to VAFIE, such a mechanism would allow Vietnam to pursue selective market opening while eliminating the potential for a “request-and-grant” mechanism.

The MoF said that, following revisions, Clause 3a of Article 8 of the draft law no longer refers to the concepts of “strategic investment projects with major impacts on socio-economic development” or “other projects.”

Instead, the relaxation of market access conditions would be determined on a sector-by-sector basis, regardless of whether a project is identified as strategic.

According to the ministry, the revised draft has established multiple layers of safeguards to eliminate the risk of discretionary application.

The draft law dossier has now been submitted to the Ministry of Justice for appraisal.


See all blog