Lumen Vietnam Fund

Blog

Credit growth slows, slips in first half of October

Credit growth slows, slips in first half of October

Credit growth across Vietnam’s banking system eased from 11.59% at the end of September to 11.44% as of October 14, indicating that lending momentum has stalled and even edged down in the short term.

Meanwhile, the State Bank of Vietnam (SBV) continues to urge banks to cut both deposit and lending rates.

Credit growth sees short-term reversal

According to information released by SBV Governor Pham Duc An at a meeting on Monday, outstanding credit to the economy reached VND20,720 trillion ($800.73 billion) as of October 14, up 11.44% from the end of 2025 and 16.73% year-on-year.

The figure was lower than the 11.59% credit growth previously reported by the SBV. Earlier in October, the central bank said system-wide outstanding credit had reached around VND20,750 trillion ($801.89 billion) as of September 30, up 11.59% from the end of 2025 and 16.69% year-on-year.

This means credit growth since the beginning of the year had fallen by around 0.15 percentage points in just the first half of October.

The development is noteworthy as Vietnam pursues an ambitious economic growth target, which is expected to drive strong demand for capital for production, business activities and investment.

Alongside the credit slowdown, pressure to cut interest rates is mounting. On October 19, the SBV held a meeting with credit institutions chaired by Governor Pham Duc An, following the issuance of Official Letter No. 9608/NHNN-CSTT on measures concerning credit institutions’ operations.

At the meeting, the governor stressed that banks must simultaneously cut operating costs, share profits and reduce funding costs to deliver meaningful lending-rate reductions. Deposit rates are a key component of funding costs; if banks continue to raise them, their room to lower lending rates will be limited.

Under the SBV’s requirements, credit institutions must initially cut listed deposit rates by at least 0.5 percentage points per year for maturities of six months or longer. They must also avoid competing to raise deposit rates in ways that create unfair competition and destabilize the money market. At the same time, banks must introduce measures to cut lending rates by 1.5-2 percentage points per year for production, business activities and priority sectors.

Notably, rate cuts are not intended to be applied uniformly. Banks must target the appropriate borrowers and extend reductions to both existing loans and new lending. The SBV also requires tighter control over credit flowing into potentially risky sectors and warns banks against lowering lending standards to pursue credit growth.

The latest directive follows several rounds of calls for lower interest rates since the beginning of the year. It also signals that regulators want to translate general instructions into more concrete action on both the funding and lending sides.

SBV has called for rate cuts six times

Since the beginning of 2026, the government and the SBV have repeatedly urged the banking system to lower interest rates. Key milestones include Directive 01/CT-NHNN issued early in the year; a meeting with 46 commercial banks on April 9; corrective and follow-up directives in May; further instructions on interest-rate support and credit in subsequent months; and the latest call on October 18. In total, the SBV has called on banks to cut interest rates six times this year.

Following the latest directive, the market has seen concrete responses in both deposit and lending rates. Among state-owned commercial banks, BIDV has launched a short-term dong lending program with rates starting at 6% per year, up to 2 percentage points below its usual rates, depending on loan maturity and sector.

Vietcombank has pledged to cut lending rates by at least 2 percentage points per year from now until the end of the year.

Agribank also launched a program on October 19 to cut lending rates by up to 2 percentage points per year, with around VND2 trillion ($77.27 million) earmarked to support customers.

Among joint-stock commercial banks, LPBank and VietBank were among the first to adjust their listed deposit rates on Monday.

LPBank cut rates by 0.5 percentage points per year for maturities of six to 12 months and by 0.6 percentage points for maturities of 13 to 18 months. Notably, it also reduced rates by 1.6-2 percentage points per year on newly disbursed short-term loans for production and business activities.

VietBank cut deposit rates by 0.5 percentage points per year for maturities of six to 36 months.

The market has also reported that ACB would adjust its deposit rate schedule from Tuesday. The specific reductions should be checked against the bank’s official rate schedule before publication.

These moves suggest that regulatory instructions are beginning to translate into concrete programs. However, the maximum reductions announced under individual programs do not mean that all customers will receive equivalent cuts in their borrowing rates.

Assessing the outlook for the remainder of 2026, brokerage VNDirect said interest rates were likely to remain relatively stable through the end of the year, with more pronounced declines from early 2027 as external pressures ease. The forecast reflects constraints from inflationary pressures, strong demand for capital and the possibility of further U.S. interest-rate increases.

Funding pressures are also making rate cuts difficult to implement evenly across the banking system. According to Bao Viet Securities (BVSC), deposit growth remains below credit growth, continuing to put pressure on banks’ funding. As a result, the SBV’s rate-cut directives may first affect preferential lending programs and listed deposit rates. For borrowing costs to decline sustainably across the broader market, however, banks will still need to improve deposit mobilization and liquidity management.


Source: Dinh Vu, Thai Ha
Latest Posts

Vietnam treasures time-tested friendship, multifaceted cooperation with Denmark: Top leader

Vietnam treasures time-tested friendship, multifaceted cooperation with Denmark: Top leader

During their meeting in Copenhagen on October 19 (local time), General Secretary and President To Lam and King Frederik X highlighted the expansion of bilateral economic, trade and investment cooperation.

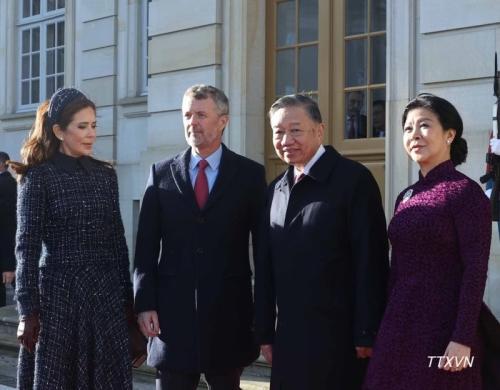
General Secretary and President To Lam and his spouse Ngo Phuong Ly met with King Frederik X and Queen Mary in Copenhagen on October 19 (local time), as part of their state visit to Denmark.

The top Vietnamese leader was quoted by the Vietnam News Agency as stating at the meeting that Vietnam attaches importance to and wants to further deepen its traditional friendship and multifaceted cooperation with Denmark, one of its key partners in Northern Europe and Europe as a whole.

King Frederik X warmly welcomed the General Secretary and President and his spouse on their state visit to Denmark, noting that it coincides with the 55th anniversary of diplomatic relations between the two countries (1971–2026) and marks an important milestone in their friendship and cooperation. The King shared fond memories of Vietnam and its people from his visits in 2009, 2011 and 2022, highlighting the Danish Royal Family’s special bond with the country, including the cherished memories of living in Hanoi of late Prince Henrik – his father, the news agency reported.

Congratulating Denmark on its development achievements, General Secretary and President Lam praised the country’s efforts to build a prosperous and modern society with a high quality of life, and take the lead in green development, innovation and social welfare. He expressed his confidence that, under King Frederik X’s reign and with the efforts of the Government and people, Denmark will continue to prosper and strengthen its important role and standing in Europe and the world.

He spoke highly of Denmark’s valuable support since the establishment of bilateral diplomatic relations in 1971 as well as in Vietnam’s post-war reconstruction, national development, Doi moi (Renewal), international integration and ongoing green transition.

Both leaders welcomed the positive development of the bilateral relations, particularly since the establishment of the Comprehensive Partnership in 2013 and the Green Strategic Partnership in 2023. Economic, trade and investment cooperation has continued to expand, with Danish companies such as LEGO, Pandora and Carlsberg operating and expanding their business in Vietnam, contributing to socio-economic development, job creation, technology transfer and sustainable green growth.

The Vietnamese leader highlighted King Frederik X’s significant contributions to the bilateral ties, noting that the King’s visit to Vietnam in 2011 as Crown Prince, marking the 40th anniversary of diplomatic relations, and his visit in 2022 with then Crown Princess Mary helped advance the bilateral ties and paved the way for the Green Strategic Partnership established in 2023.

King Frederik X shared General Secretary and President Lam’s views on leveraging the two countries’ complementary strengths and expanding cooperation in trade, investment, science and technology, innovation, energy transition, green and marine economy, education and training, and people-to-people exchanges. The Vietnamese leader expressed his hope that the King will continue encouraging Danish businesses and organizations to strengthen cooperation and investment in the Southeast Asian country.

The two sides noted that, beyond practical cooperation, the bilateral ties are underpinned by friendship, trust and close people-to-people connections built over generations. General Secretary and President Lam praised the Danish Royal Family’s role in promoting cultural and artistic exchanges and people-to-people links, expressing his wish that both countries will further nurture these shared values and deepen their friendship.

On this occasion, the General Secretary and President invited King Frederik X and Queen Mary to visit Vietnam soon to witness the country’s remarkable transformation and the further expansion of bilateral relations.

General Secretary and President To Lam and his spouse Ngo Phuong Ly, as well as King Frederik X and Queen Mary expressed their confidence that Vietnam–Denmark friendship and cooperation will grow further, bringing benefits and prosperity to the people of both countries and contributing to peace, stability, cooperation and sustainable development in the regions and the world.


Vietnam central bank orders banks to cut listed deposit rates by at least 0.5 percentage points

Vietnam central bank orders banks to cut listed deposit rates by at least 0.5 percentage points

The State Bank of Vietnam (SBV) has ordered credit institutions to cut listed deposit interest rates by at least 0.5 percentage points per year for maturities of six months or longer, while lowering lending rates by 1.5-2 percentage points for production, business activities and priority sectors.

Banks that fail to comply could face cuts to their credit growth targets.

The SBV issued a document on Sunday requiring credit institutions and foreign bank branches to implement coordinated measures to maintain macroeconomic stability, control inflation, support economic growth, and ensure the safety of the banking system.

Accordingly, credit institutions must strictly comply with the government's, the prime minister's and the SBV's regulations and directives on interest rates. They must mobilize all available resources, reduce costs, share profits and take decisive, coordinated measures to bring down interest rates across the market.

As an immediate measure, banks must cut listed deposit rates by at least 0.5 percentage points per year for maturities of six months or longer. The SBV stressed that banks must not engage in a race to raise deposit rates or resort to unfair competition that could destabilize financial and monetary security.

On lending rates, the regulator requires banks to reduce rates for customers, with cuts of 1.5-2 percentage points per year focused on production, business activities and priority sectors.

The directive requires banks to adjust both sides of their business operations simultaneously by lowering funding costs and lending rates, while maintaining liquidity safety, credit quality and operational efficiency.

The SBV also instructed credit institutions to maintain a balanced relationship between deposits and lending, regularly review their funding structures by currency and maturity, and diversify funding channels.

Banks must control liquidity risks and maturity mismatches while increasing the proportion of medium- and long-term funding to ensure a sustainable balance between funding sources and their use.

The push to lower interest rates does not mean a relaxation of risk management requirements. Instead, banks must proactively restructure their funding, reduce costs and improve operational efficiency to create room for rate cuts.

Banks told to tighten controls on riskier lending

Regarding credit allocation, the SBV requires lending growth to be safe and effective, with funding directed towards production, business activities, priority sectors and key drivers of economic growth.

Banks are encouraged to lend to feasible key projects that support socio-economic development, while prioritizing science and technology, innovation, digital transformation, green transition, the digital economy, green economy, circular economy, education and training, and cultural industries.

For large-scale projects, the SBV encourages syndicated lending. However, it stressed that credit institutions must not lower lending standards or sacrifice credit quality to expand loan volumes.

The directive places particular emphasis on risk control. Credit institutions must closely monitor lending to potentially high-risk sectors and customers or customer groups with large outstanding loan balances.

Banks must pay particular attention to concentration risks among customer groups and related parties, credit exposure by customer, and large-scale projects. They should monitor groups of customers sharing one or more of the following characteristics: the same manager or legal representative, or an owner holding more than 5% of a customer's charter capital; shared collateral or the same collateral owner; capital concentrated in the same project; or a common source of debt repayment.

Banks must diversify their credit portfolios and combine these assessments with indicators such as property price movements, market liquidity, project inventories and corporate bond issuance conditions. These measures are intended to help identify violations, shortcomings and emerging risks early, enabling banks to take appropriate corrective and risk-control measures.

The SBV also requires strict controls on lending to organizations and individuals seeking funds for the following purposes:

(i) Paying for capital contributions to, or purchasing or acquiring transferred capital stakes in, limited liability companies or partnerships; or contributing capital to, purchasing or acquiring transferred shares in joint-stock companies that are not listed on the stock market or registered for trading on the UPCoM (unlisted public companies market) trading system.

(ii) Paying capital contributions under capital contribution agreements, investment cooperation contracts or business cooperation contracts to implement investment projects that are not legally eligible for commercialisation at the time the credit institution decides to extend the loan.

(iii) Providing financial compensation or reimbursement, except for certain loans that fully meet the prescribed conditions.

The SBV emphasized that risk control and the safety of the credit institution system are critically important to economic development, national security, public order and social safety.

It said banking legislation would continue to be refined to ensure effective and substantive oversight of share ownership, customers and related customer groups, and the purposes for which borrowed funds are used.

For the remainder of 2026, credit institutions that fail to comply strictly with the government's, the prime minister's or the SBV's interest rate directives, or engage in unfair competition that destabilises markets and creates risks for banking operations, could face sanctions under the law and additional measures depending on the nature and severity of the risks.

These measures include reviewing their credit growth targets for the remainder of 2026 and assigning lower credit growth targets for 2027, as well as requiring them to comply with one or more prudential ratios set at levels higher than the prescribed requirements.


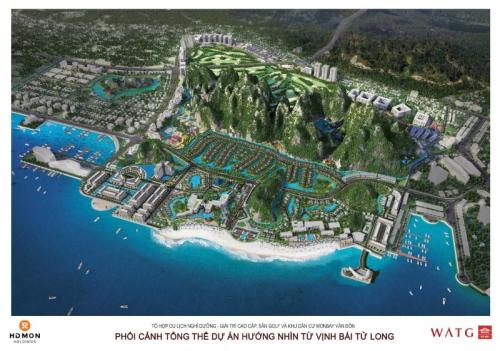
Quang Ninh urges fast-tracking of $1 billion Monbay Van Don project

Quang Ninh urges fast-tracking of $1 billion Monbay Van Don project

The high-end tourism, resort and entertainment complex, golf course and residential area is planned to include 236 villas, 257 townhouses, more than 2,600 high-rise apartments and 606 social housing units.

Northern Quang Ninh city's authorities have urged the investor of the Monbay Van Don complex to accelerate preparations and begin construction as soon as all regulatory requirements are met, with groundbreaking targeted for 2026.

The project, officially named the Monbay Van Don high-end tourism, resort and entertainment complex, golf course and residential area, is being developed by Hai Dang Real Estate Investment Company Limited.

With total investment exceeding VND24.883 trillion (nearly $1 billion), the development is planned to include 236 villas, 257 townhouses, more than 2,600 high-rise apartments and 606 social housing units.

Once completed, the complex is expected to accommodate approximately 3,000 overnight guests per day and around 9,800 residents.

Quang Ninh authorities have instructed the city’s Department of Agriculture and Environment to guide the investor through land allocation and leasing procedures, promptly appraise eligible applications and submit them for approval. The department is also tasked with determining land prices and related financial obligations, facilitating the handover of land on site, and guiding procedures for allocating sea areas required for the project’s land reclamation component.

The investor has also been asked to complete the project’s feasibility study report and prepare a detailed implementation schedule specifying key milestones, deadlines and responsibilities. The schedule must be submitted to the Van Don Special Zone administration and relevant authorities for approval and monitoring.

Authorities have called on the investor to coordinate closely with local officials and relevant agencies to ensure construction can commence in 2026, once all legal conditions have been satisfied.


See all blog